
Finance
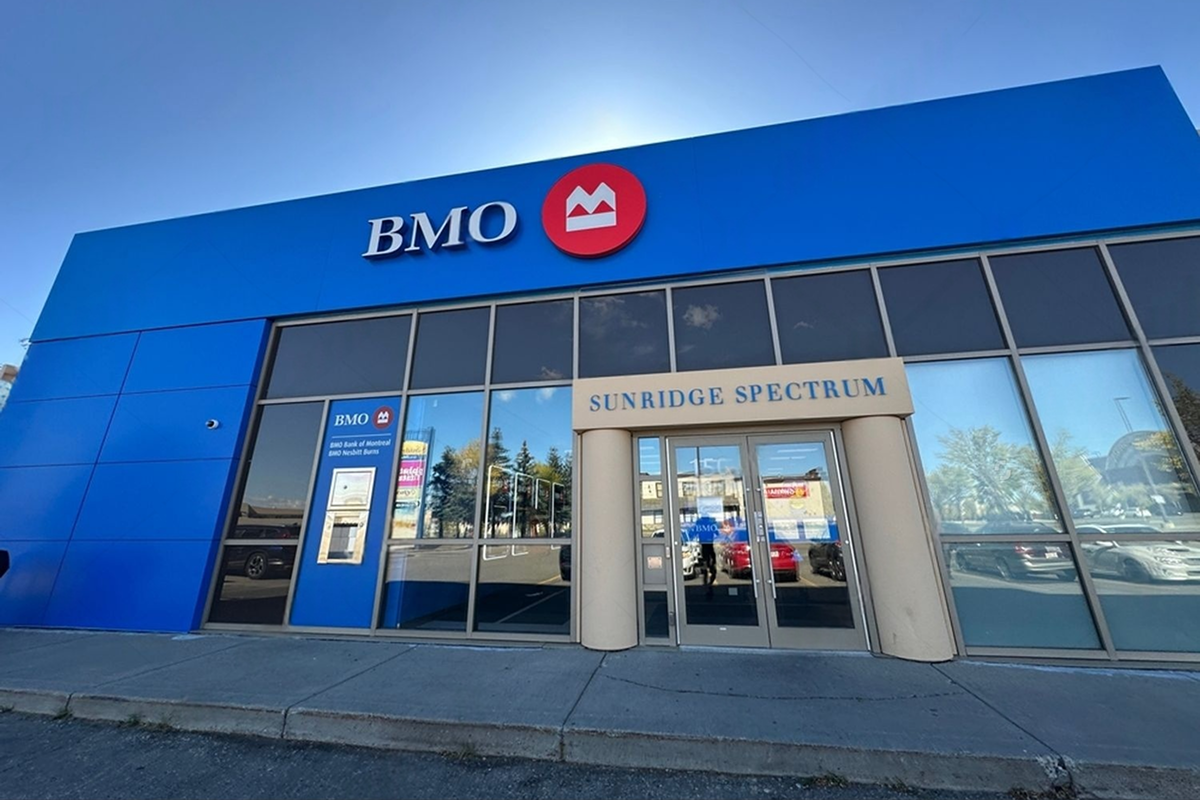
For globally mobile families and internationally active entrepreneurs, Bank of Montreal is best assessed as a potential component of a wider financial architecture. Its Canadian roots and US operations can be useful for clients with North American business interests, property holdings or recurring dollar-denominated obligations. Yet geographic reach should not be confused with seamless cross-border protection. The value of a banking relationship depends on the services provided, the legal entity responsible for them and how effectively those services connect with the client’s wider wealth structure.
BMO operates across Canada and the United States, serving personal, commercial and institutional clients. This reach can be relevant to entrepreneurs managing subsidiaries in both markets, families with property on either side of the border, or executives receiving income in multiple currencies.
A banking relationship spanning two markets may reduce administrative friction when managing payments, financing and day-to-day liquidity. However, the presence of one brand across jurisdictions does not mean every account is held by the same legal entity or governed by identical terms. Products, eligibility criteria and protections can differ between Canadian and US operations.
Before consolidating accounts, establish which entity provides each service, where the account is legally maintained and which jurisdiction governs the contractual relationship. This basic mapping helps prevent assumptions about protection, access or dispute resolution from carrying over incorrectly between countries.
BMO’s scale and diversified business lines provide context for assessing the institution, but size alone does not establish that a particular account or financial arrangement is suitable. Clients should consider capital strength, asset quality, funding conditions, risk controls and the bank’s exposure to changing economic conditions.
Equally important is the distinction between deposits and investment assets. Deposit-protection arrangements depend on the jurisdiction, eligible institution, account category and applicable limits. Securities held in custody are subject to a different legal and operational framework. Neither should be assumed to receive identical protection simply because both appear within a bank’s online platform.
For substantial cash balances, confirm the applicable protection regime and understand how balances are treated across relevant entities and account categories. For investment holdings, review custody arrangements, account documentation and the procedures that would apply if the institution or a service provider experienced disruption.
North American banking can introduce several currency considerations for a client whose wealth is measured or spent in Swiss francs. US-dollar assets may support American business expenses or investments, while Canadian-dollar balances may be appropriate for Canadian liabilities. The risk arises when currency holdings are driven by convenience rather than expected obligations.
Map recurring expenses, debt payments, tax liabilities and planned capital transfers by currency. This clarifies how much liquidity is needed in each market and where exchange-rate movements could create a mismatch. It also helps distinguish operational cash from longer-term investment capital.
Cross-border reporting requires equal discipline. Canadian, US and Swiss tax and reporting obligations depend on residence, citizenship, entity structure and the nature of the accounts. A banking relationship does not determine these obligations. Coordinate with qualified tax advisers before opening accounts, moving assets between entities or changing residence.
A Swiss private bank may provide international custody, consolidated wealth oversight and coordination with other advisers, depending on the mandate. BMO may fulfil a different role by supporting North American transactions, local credit requirements and regional liquidity. Maintaining both relationships can be rational when their functions are clearly defined.
The practical test is operational resilience. Confirm that authorised signatories are current, payment escalation routes are documented and essential expenses can be met if one institution temporarily restricts access or requires additional compliance information. Keep beneficial-ownership and source-of-funds records consistent across institutions, while sharing sensitive information only through appropriate channels.
Bank of Montreal’s cross-border presence may offer useful infrastructure for internationally connected clients. The decision to use it should rest on a clear assessment of legal structure, service requirements, currency needs and risk concentration—not on the assumption that a large international bank can replace a coordinated wealth-management framework.
For a confidential discussion regarding your cross-border banking structure, international liquidity and long-term wealth-preservation strategy, contact our senior advisory team.
 Previous Post
SKN | ANZ Bank’s Transformation: What International Wealth Holders Should Review Before Relying on an Australian Banking Relationship
 Next Post
SKN | BNP Paribas and International Wealth: How to Evaluate a European Banking Relationship Within a Swiss Strategy
October 19, 2026

October 19, 2026
October 19, 2026
October 19, 2026
SKN | Raiffeisen Switzerland’s Stronger Credit Profile: What HNWIs Should Assess Beyond the AA- Rating
SKN | Kuwait’s Mortgage Market Opens to Banks: What International Wealth Holders Should Assess Before Entering
SKN | BNP Paribas and International Wealth: How to Evaluate a European Banking Relationship Within a Swiss Strategy
 Optimized by Seraphinite Accelerator



