
Finance
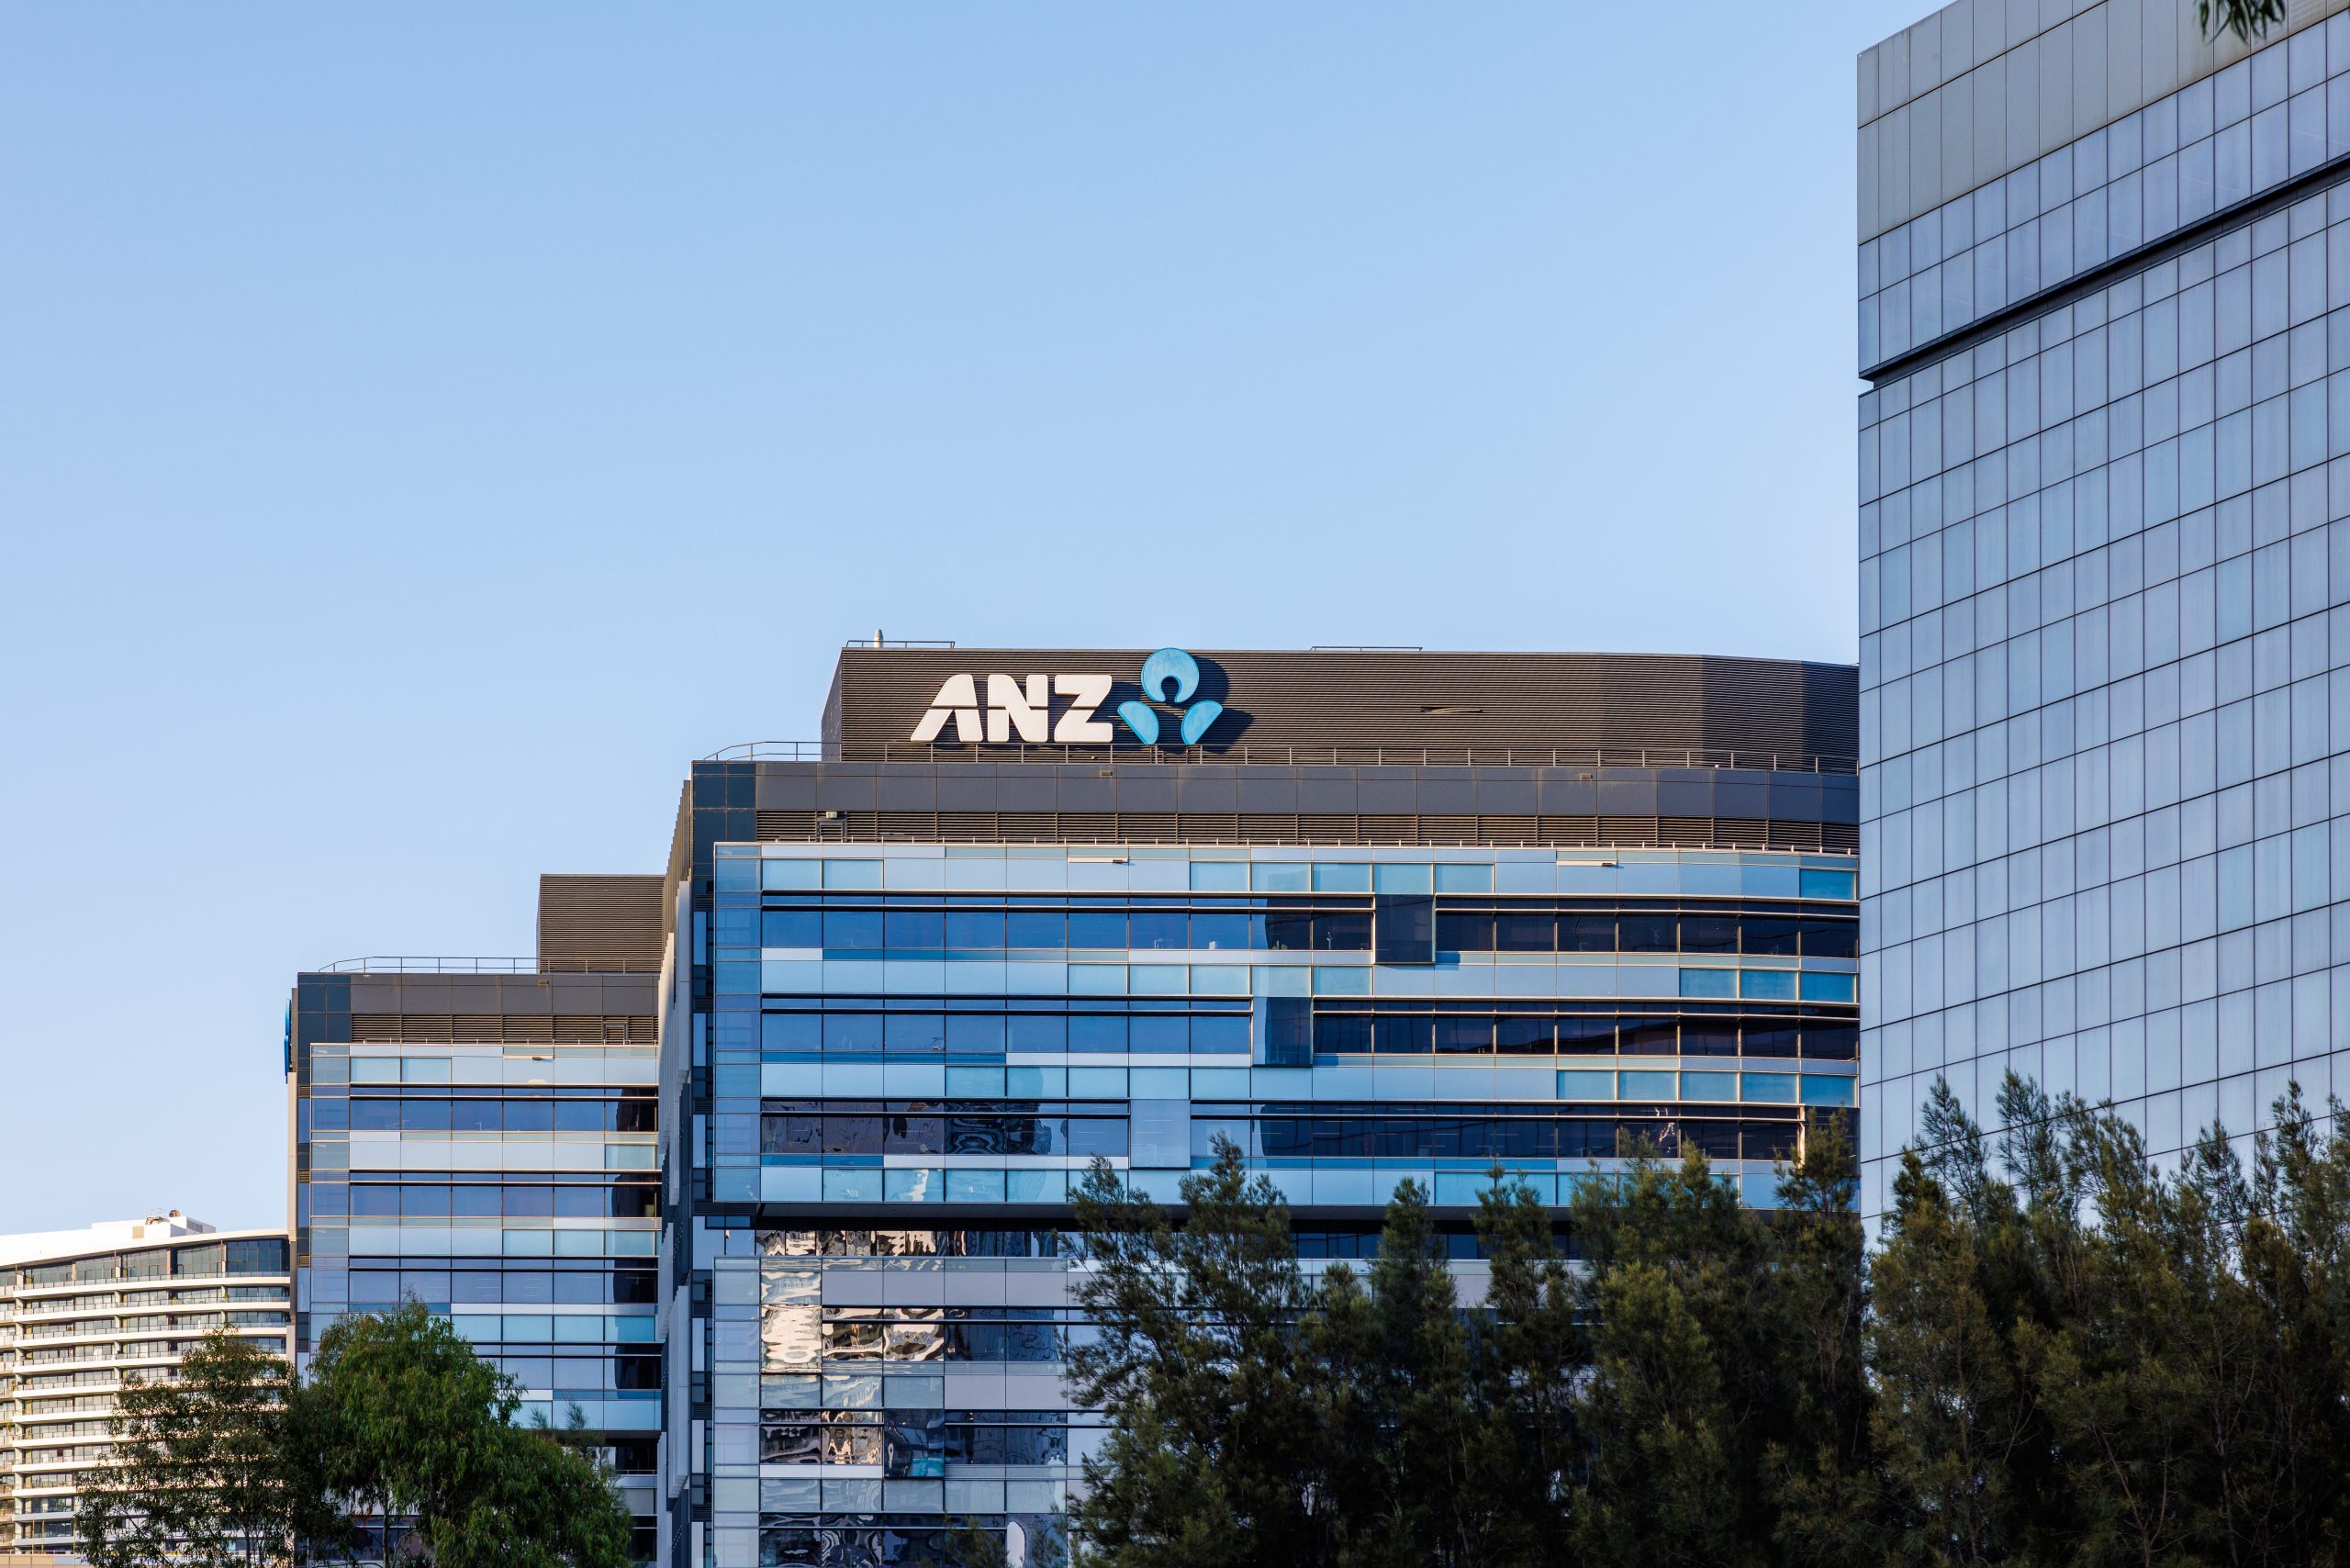
For entrepreneurs, executives and globally mobile families, ANZ Bank is relevant not simply as one of Australia’s major financial institutions, but as part of the infrastructure connecting regional business activity with international wealth. Its strategic transformation raises a practical question for clients: will the bank’s pursuit of greater efficiency translate into dependable service, stronger controls and effective support for increasingly complex financial needs?
The answer requires more than a review of annual profit. Clients should examine the bank’s financial resilience alongside its execution risks, then assess how their own banking arrangements would perform under operational disruption, currency volatility or tighter compliance scrutiny.
ANZ’s A$5.89 billion statutory profit for the 2025 financial year was 10% lower than the previous year. Significant items totalled A$1.1 billion, reflecting regulatory matters and actions to simplify the business. These figures should not be read in isolation: statutory earnings can be affected by exceptional costs, while underlying performance may provide a different view of recurring profitability.
For wealth holders, neither measure provides a complete assessment of safety. Capital adequacy, funding stability, asset quality, governance and the ability to resolve control weaknesses also matter. A strong capital position can provide a buffer against losses, but it does not eliminate legal, operational or market risk.
The more useful question is whether ANZ can improve efficiency while maintaining robust controls and reliable service. That balance is particularly important for clients whose businesses depend on time-sensitive payments, credit facilities or uninterrupted access to working capital.
ANZ’s stated strategy combines customer experience, organisational simplification, resilience and financial performance. It also includes integrating Suncorp Bank, expanding its ANZ Plus digital platform and strengthening non-financial risk management.
These initiatives may improve efficiency, but strategic plans do not guarantee consistent execution. Changes to systems, teams and internal processes can create temporary friction, particularly for businesses with complex payment approvals or multiple authorised users.
Clients should establish whether their specific accounts, lending arrangements and digital banking services are affected by any changes. Confirm who can resolve urgent payment issues, how access is restored if an authorised signatory is unavailable, and whether contingency procedures are documented. For family offices and international businesses, these operational details are part of risk management, not administrative housekeeping.
An Australian banking relationship can serve a clear purpose: receiving local income, paying operating expenses, financing regional activities or holding liquidity for Australian-dollar obligations. Problems arise when convenience allows these functions to become concentrated in a single institution without a deliberate contingency plan.
Clients should map their deposits, credit facilities, custody relationships and payment dependencies by legal entity and jurisdiction. Deposit protection and the treatment of investment assets differ according to the product and applicable rules. A bank’s international brand does not make these arrangements interchangeable across countries.
Currency exposure deserves equal attention. Australian-dollar balances may be appropriate for Australian liabilities, but their value can fluctuate against Swiss francs, euros and other currencies used to fund family expenses or measure wealth. Matching cash holdings to expected obligations can reduce unnecessary currency mismatches without requiring short-term exchange-rate predictions.
For clients with interests in Australia and Europe, ANZ and a Swiss private bank may serve complementary roles. ANZ can support regional operating requirements, while a Swiss institution may coordinate international custody, liquidity and broader wealth-management needs, depending on the services agreed.
The objective is not to duplicate every service. It is to ensure that critical payments, liquidity and financial records remain accessible if one relationship experiences disruption. Review account mandates, beneficial-ownership documentation, source-of-funds records and escalation contacts across both institutions. Any additional banking arrangement should have a clear operational purpose and be consistent with applicable tax, reporting and compliance obligations.
ANZ’s transformation is ultimately a test of execution: whether a major bank can simplify its operations while strengthening accountability and maintaining client confidence. For internationally exposed families, disciplined oversight of the banking structure is more valuable than reacting to individual headlines.
For a confidential discussion regarding your cross-border banking structure, international liquidity and long-term wealth-preservation strategy, contact our senior advisory team.

October 18, 2026

October 18, 2026
October 17, 2026
October 16, 2026
SKN | J.P. Morgan Retirement Strategist Challenges the 4% Rule as Longevity Risk Reshapes Retirement Planning
SKN | Banco Santander Advances Blockchain Financing as Share Buybacks Support Investor Confidence
SKN | Whirlpool Stock Faces Further Pressure as Wells Fargo Cuts Price Target to $30
 Optimized by Seraphinite Accelerator



