
Finance
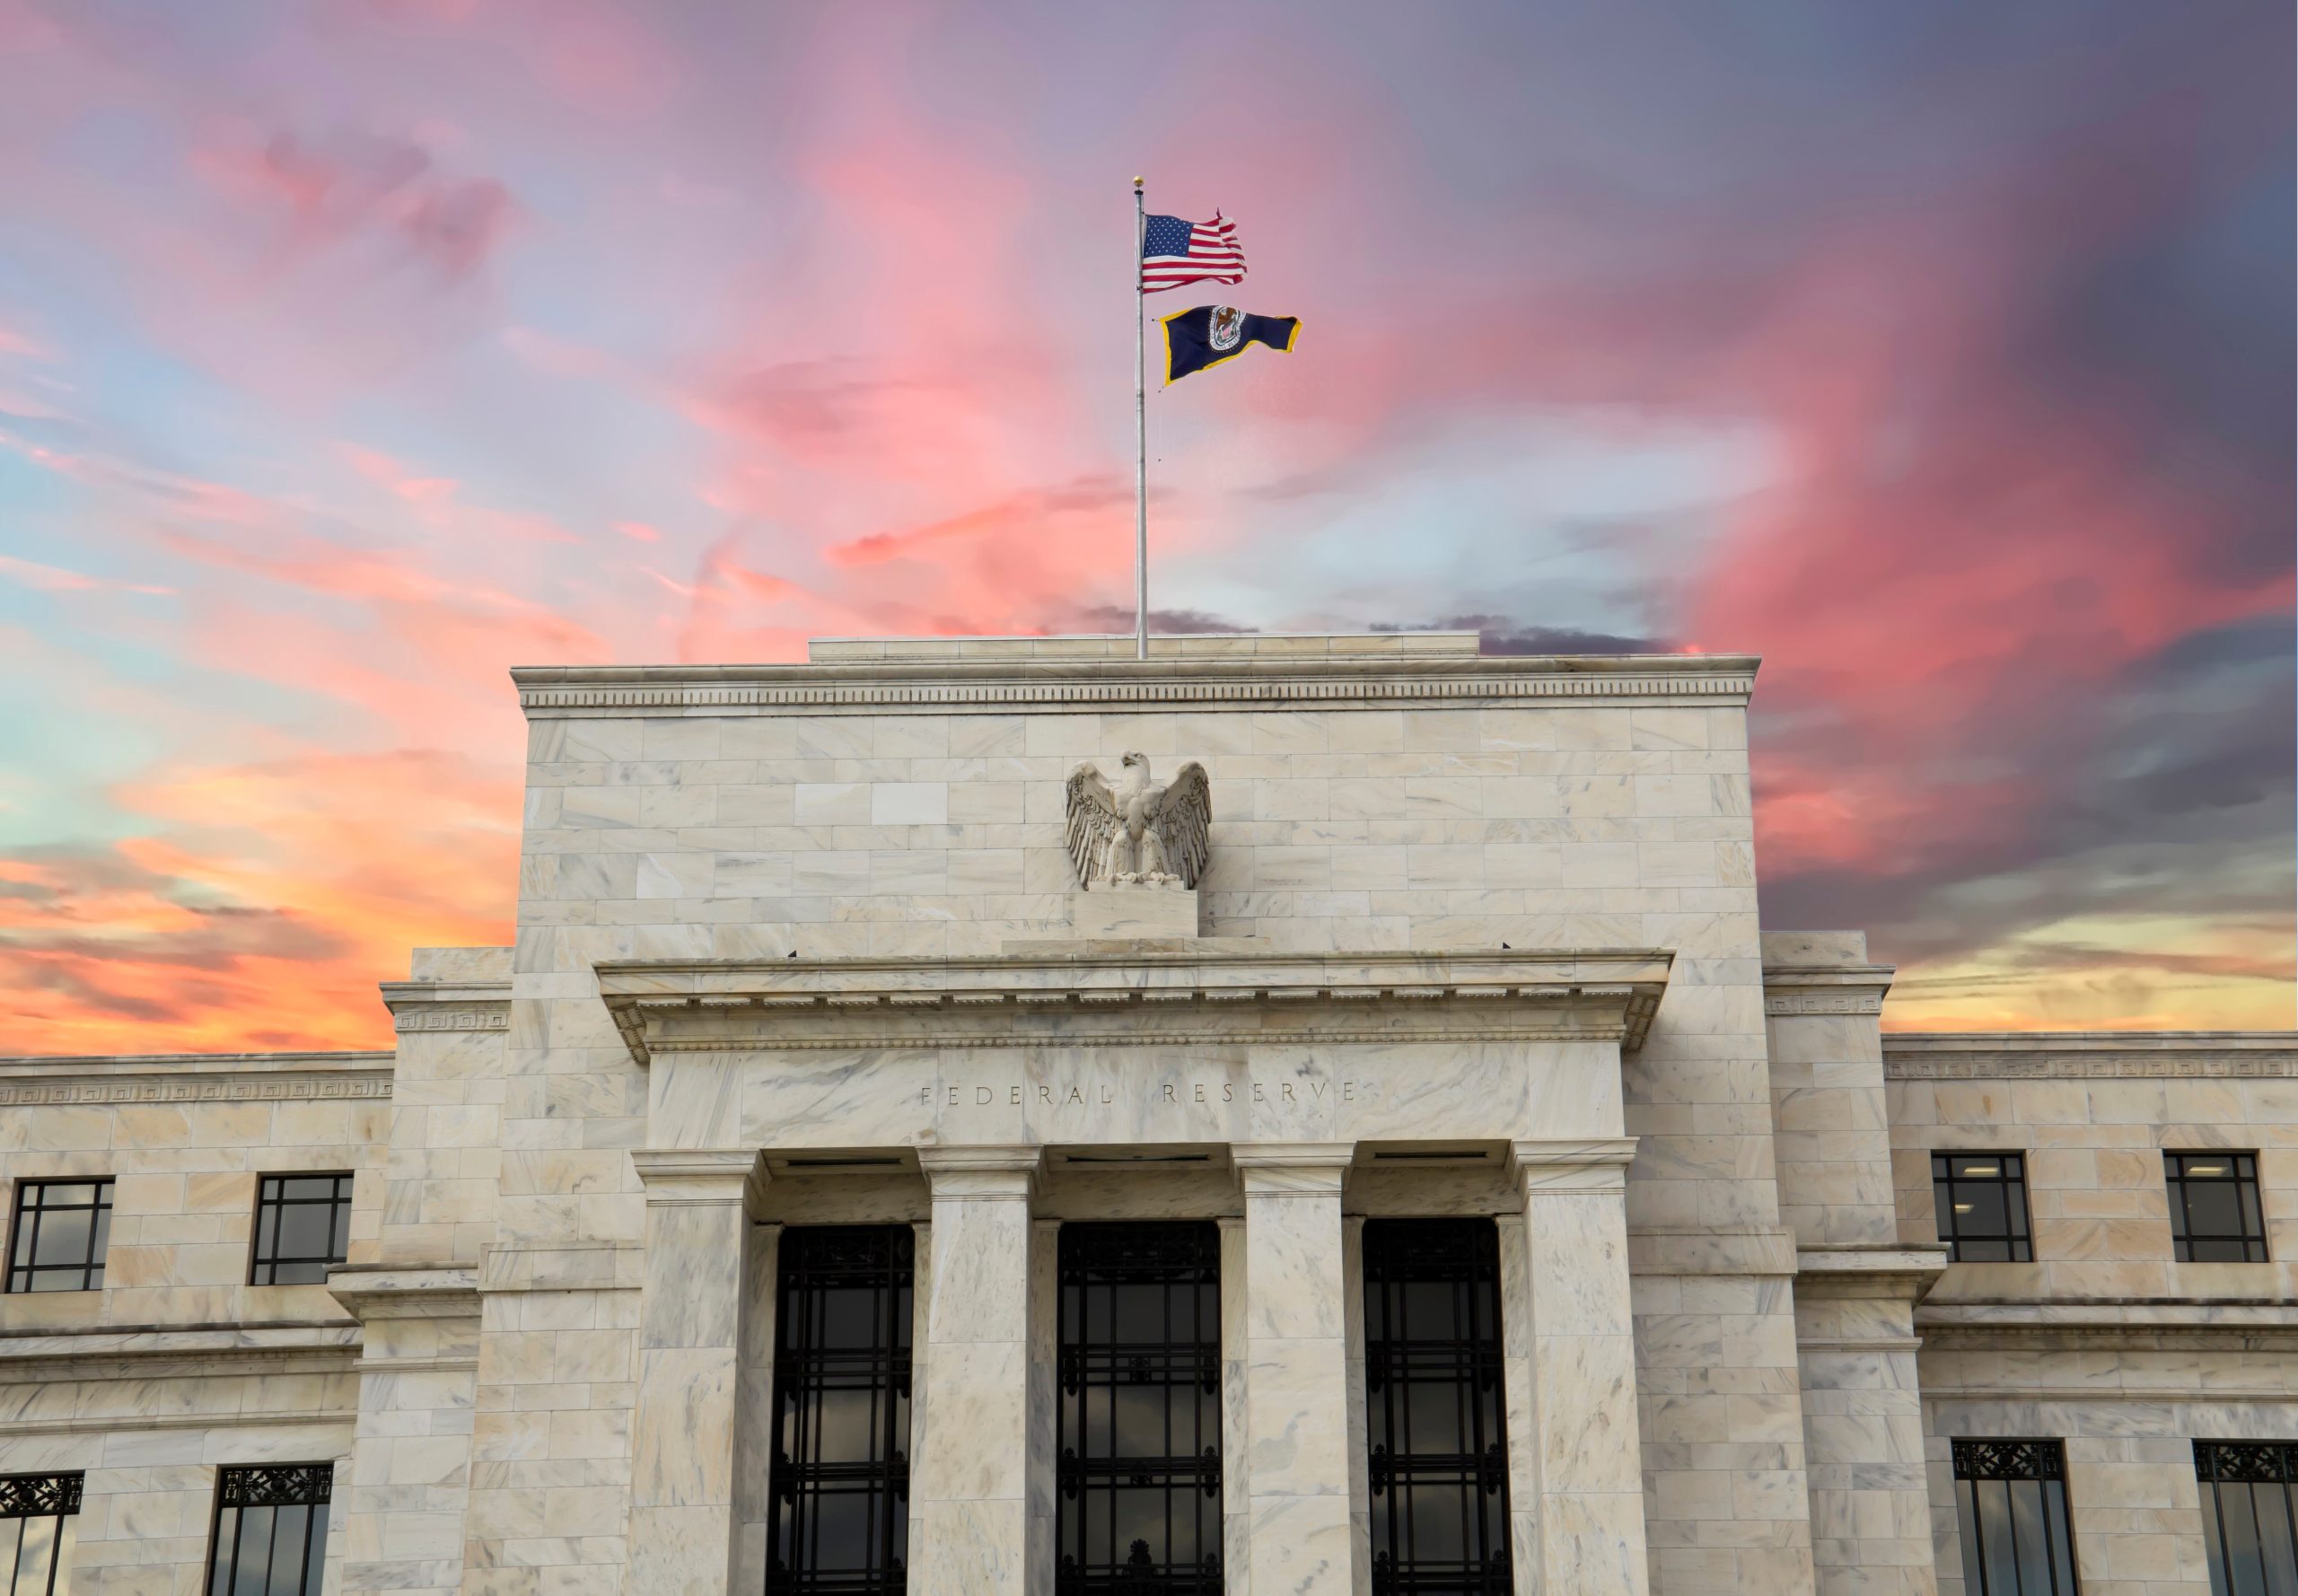
Support from banking lobby groups for Federal Reserve Vice Chair for Supervision Michelle Bowman’s plans to modernise bank supervision reflects an important debate in US finance: how to make regulation more predictable without weakening the system’s ability to withstand stress. For internationally active families, the outcome matters beyond Washington. Supervisory policy can influence how banks allocate capital, assess risk, extend credit and manage relationships involving multiple jurisdictions.
Bank supervision affects more than regulatory reporting. It shapes how institutions evaluate risk, document decisions and allocate resources across business lines. A more consistent supervisory process could reduce uncertainty and unnecessary compliance friction. Banks may then have greater clarity when planning lending, capital deployment and client services.
However, modernisation does not automatically mean deregulation, nor does industry support prove that a proposed change will improve financial stability. The relevant questions are which supervisory practices change, how those changes are implemented and whether core safeguards remain effective.
For HNWIs, a bank that operates more efficiently may offer faster credit decisions or smoother onboarding. Yet the quality of a banking relationship cannot be judged by speed alone. Capital strength, liquidity, funding concentration, risk controls and governance remain central to assessing institutional resilience.
This distinction is particularly relevant when a bank provides several services to the same family, such as deposits, custody, securities-backed lending and corporate financing. Supervisory reform may change the economics of those services, but it does not remove the need to understand the combined exposure to one institution.
International banking groups operate through different subsidiaries, branches and booking centres. A change in Federal Reserve supervisory policy will not necessarily affect every entity in the same way. The impact depends on the institution’s structure, regulatory status and activities.
Families with US investments, dollar liquidity or American operating businesses should establish which entity holds their assets, which bank provides credit and which regulator oversees each relationship. The global brand is not a substitute for understanding the legal counterparty.
Zurich and Geneva private banks can serve as a central wealth-management and governance layer while US institutions provide local services, dollar payments or financing. The objective is not to remove US exposure, but to ensure that the family’s entire financial architecture does not depend on one regulatory environment or banking group.
Effective diversification requires more than opening accounts at different institutions. Families should examine shared parent groups, custody arrangements, correspondent banks, payment channels and credit dependencies. Otherwise, apparently separate relationships may remain exposed to the same underlying disruption.
As the Federal Reserve considers supervisory reform, HNWIs should focus on practical consequences rather than policy rhetoric. Review whether changes affect credit availability, onboarding requirements, reporting obligations or the services provided by specific banking entities. Confirm that liquidity and payment access remain workable if one relationship becomes more restrictive.
The strategic objective is a wealth structure that can benefit from more efficient banking without relying on regulatory relaxation as a substitute for sound risk management. In cross-border private banking, flexibility is valuable only when the underlying controls remain robust.
For a confidential discussion regarding your cross-border banking structure, US regulatory exposure and Swiss wealth-management architecture, contact our senior advisory team.

October 9, 2026

October 8, 2026

October 8, 2026

October 8, 2026
SKN | Standard Chartered Bangladesh Sale: What Employee Unrest Reveals About Banking Transition Risk
SKN | Citigroup Q3 Earnings Outlook Highlights Growth Potential and Transformation Risks
SKN | Lloyds Bank Removes £15 Monthly Premier Account Fee While Retaining Eligibility Requirements
 Optimized by Seraphinite Accelerator



